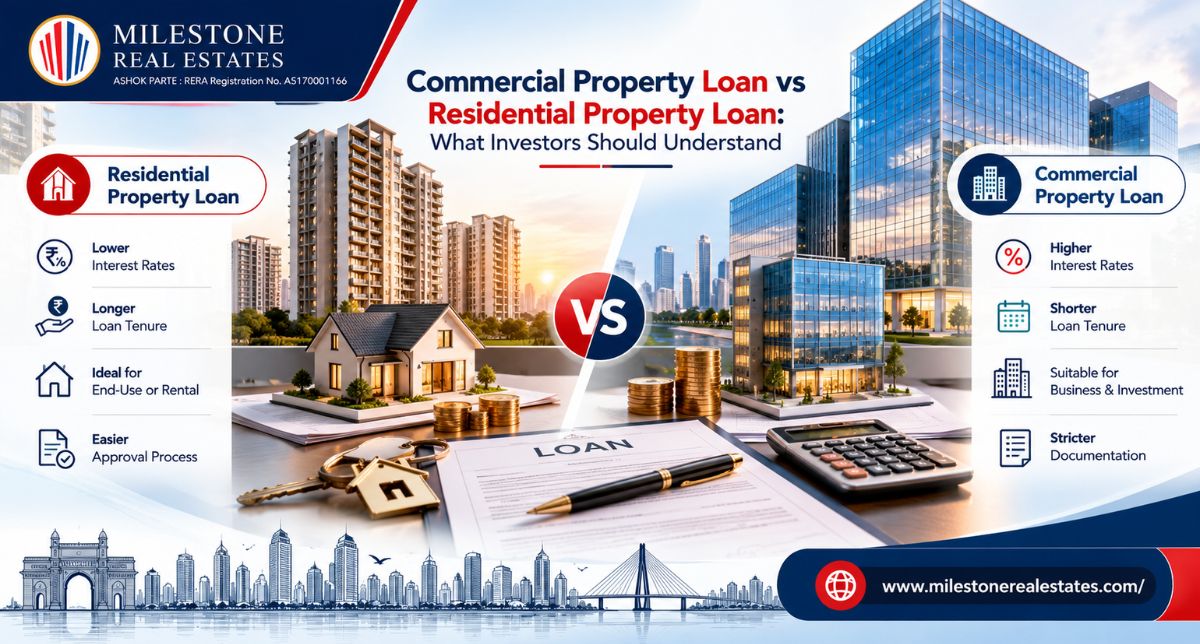
Buying property often requires significant financial planning, and choosing the right loan can influence the overall investment. While residential loans help buyers purchase homes, commercial loans are designed for properties used for business purposes. Understanding the differences helps buyers compare financing options before making a commitment.
For anyone considering Commercial Property Loan vs Residential Property Loan, the decision should depend on the property's intended use, financial capacity, repayment comfort and long-term objectives.
1. Understanding Residential Property Loans
A residential property loan is generally used to purchase a home, apartment or other eligible residential property. Buyers may use this financing to purchase a property for personal occupation or, depending on the lender's terms, rental purposes.
A Residential Property Loan may appeal to first-time homebuyers and investors seeking residential rental income. Lenders evaluate several factors, including the applicant's income, credit history, existing financial commitments and the property's legal documentation.
The loan amount and repayment period depend on the lender's policies and the applicant's eligibility. Buyers should compare the total borrowing cost rather than choosing a loan solely because the monthly instalment appears affordable.
2. Understanding Commercial Property Loans
A Commercial Property Loan is associated with eligible properties intended for commercial use, such as offices, shops and certain business premises. Depending on the lender and product, financing may be available for purchasing or otherwise funding eligible commercial property.
These loans may have different eligibility requirements, repayment structures and financing limits compared with residential loans. Lenders can examine the borrower's income, business financials, credit profile and property documents.
Investors should confirm whether the property and proposed transaction qualify under the lender's specific loan product. A residential apartment and a commercial office should not automatically be assumed to have identical financing conditions.
3. Down Payment and Loan Amount
The required contribution from the buyer can differ between residential and commercial financing. The amount depends on the lender, property valuation, borrower profile and applicable loan-to-value limits.
Commercial buyers should be prepared for a potentially larger upfront contribution, although the actual requirement varies by case. They should also budget for registration expenses, applicable taxes, legal checks, interior work and other purchase-related costs.
Before finalising a property, calculate how much money will remain available after the purchase. Using all available savings for a down payment can leave an investor unprepared for unexpected expenses or periods without rental income.
4. Interest Rates and Repayment Terms
Interest rates are an important part of any borrowing decision. The rate offered can depend on the lender, loan product, credit profile, security and prevailing market conditions.
A Commercial Property Loan may carry different pricing and repayment conditions from a residential loan. However, commercial financing is not automatically more expensive in every situation. Buyers should compare actual offers from multiple lenders.
Review the interest rate, loan tenure, processing fees, prepayment conditions and any other applicable charges. Also understand whether the rate is fixed or floating and how changes could affect future instalments.
5. Eligibility and Documentation
Lenders assess repayment capacity before approving a loan. For salaried applicants, income records and employment details may be important. Self-employed applicants may need business financial statements, income tax returns and supporting financial documents.
For Property Loan Eligibility, lenders can also consider credit history, existing loans and the property's valuation and legal status.
Commercial property purchases may require additional documents relating to the business, property use or transaction, depending on the lender's requirements. Investors should obtain a document checklist early to reduce delays during the application process.
6. Rental Income and Investment Planning
Rental income may support loan repayments, but it should not be treated as guaranteed. Residential properties may attract families or individuals, while commercial premises may suit offices, retailers or other businesses.
Before choosing Commercial Property Investment, research local rental demand, vacancy periods, maintenance costs and the time required to find suitable tenants.
A broader Real Estate Investment plan should account for periods without rental income, repairs, property taxes and other ownership expenses. Buyers should ensure they can manage repayments even if the property remains vacant temporarily.
7. Which Loan Should Investors Choose?
The right loan depends on the property's purpose and the borrower's financial situation. A residential loan may suit someone purchasing a home, while commercial financing may be appropriate for an eligible office or shop.
Compare written loan offers, assess the complete cost and review the repayment schedule before signing. If necessary, consult a qualified financial adviser to understand how the borrowing fits your wider financial plans.
Conclusion
Understanding the differences between residential and commercial property loans helps buyers make better-informed decisions. Compare eligibility, upfront costs, interest rates, repayment terms and rental prospects before proceeding.
The best financing option is one that suits the property's intended use and remains manageable throughout the loan period.